Planner · WTR 1998
Staff holiday planner
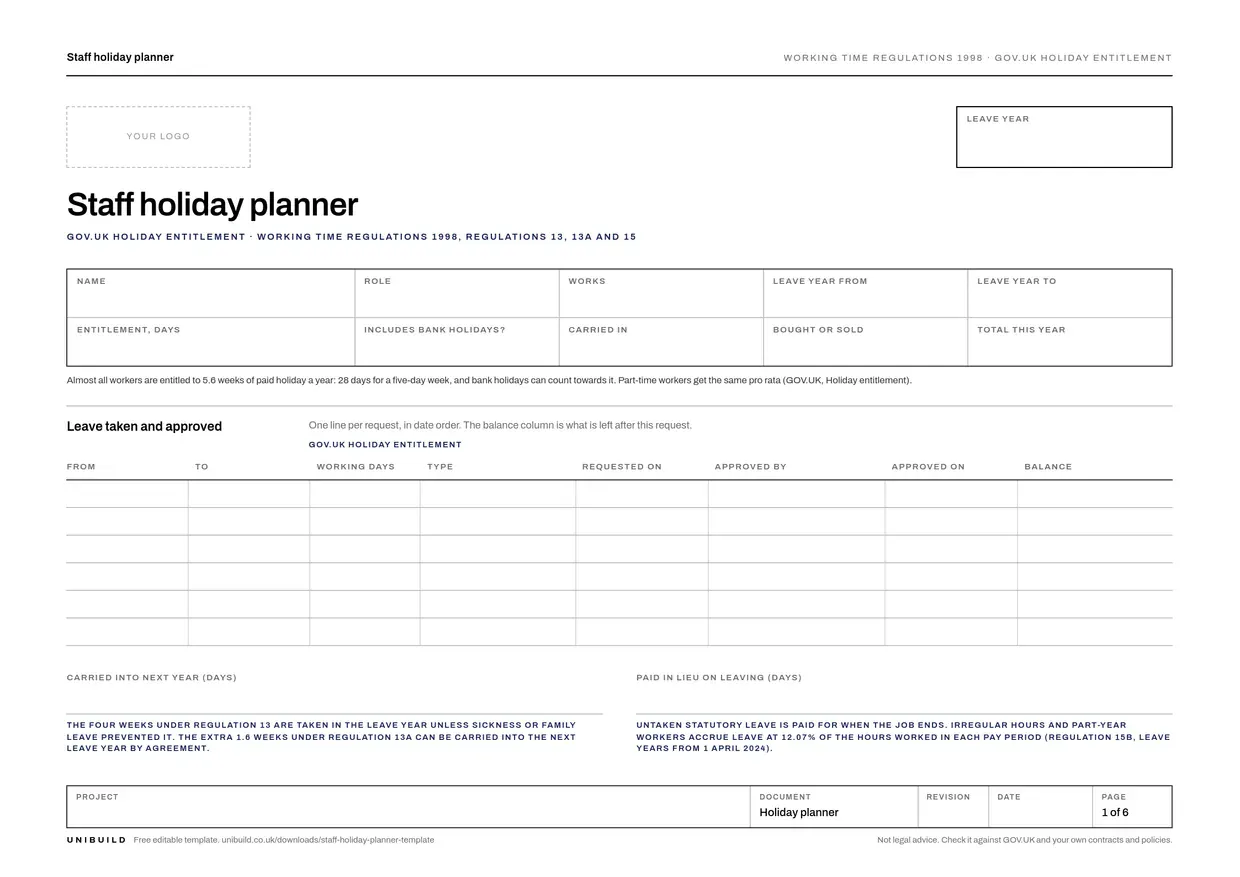
A leave record per person with entitlement, carry-over and every request approved, a team planner a quarter per page, and the 2026 and 2027 bank holidays by nation. As a PDF, Word and an Excel workbook.

A CIS payment and deduction statement tells a subcontractor what they were paid in the tax month, the cost of materials, and the CIS deducted for HMRC. This one carries every particular the regulations require, with a guidance page, as an editable PDF and a Word document, free to use and reuse.
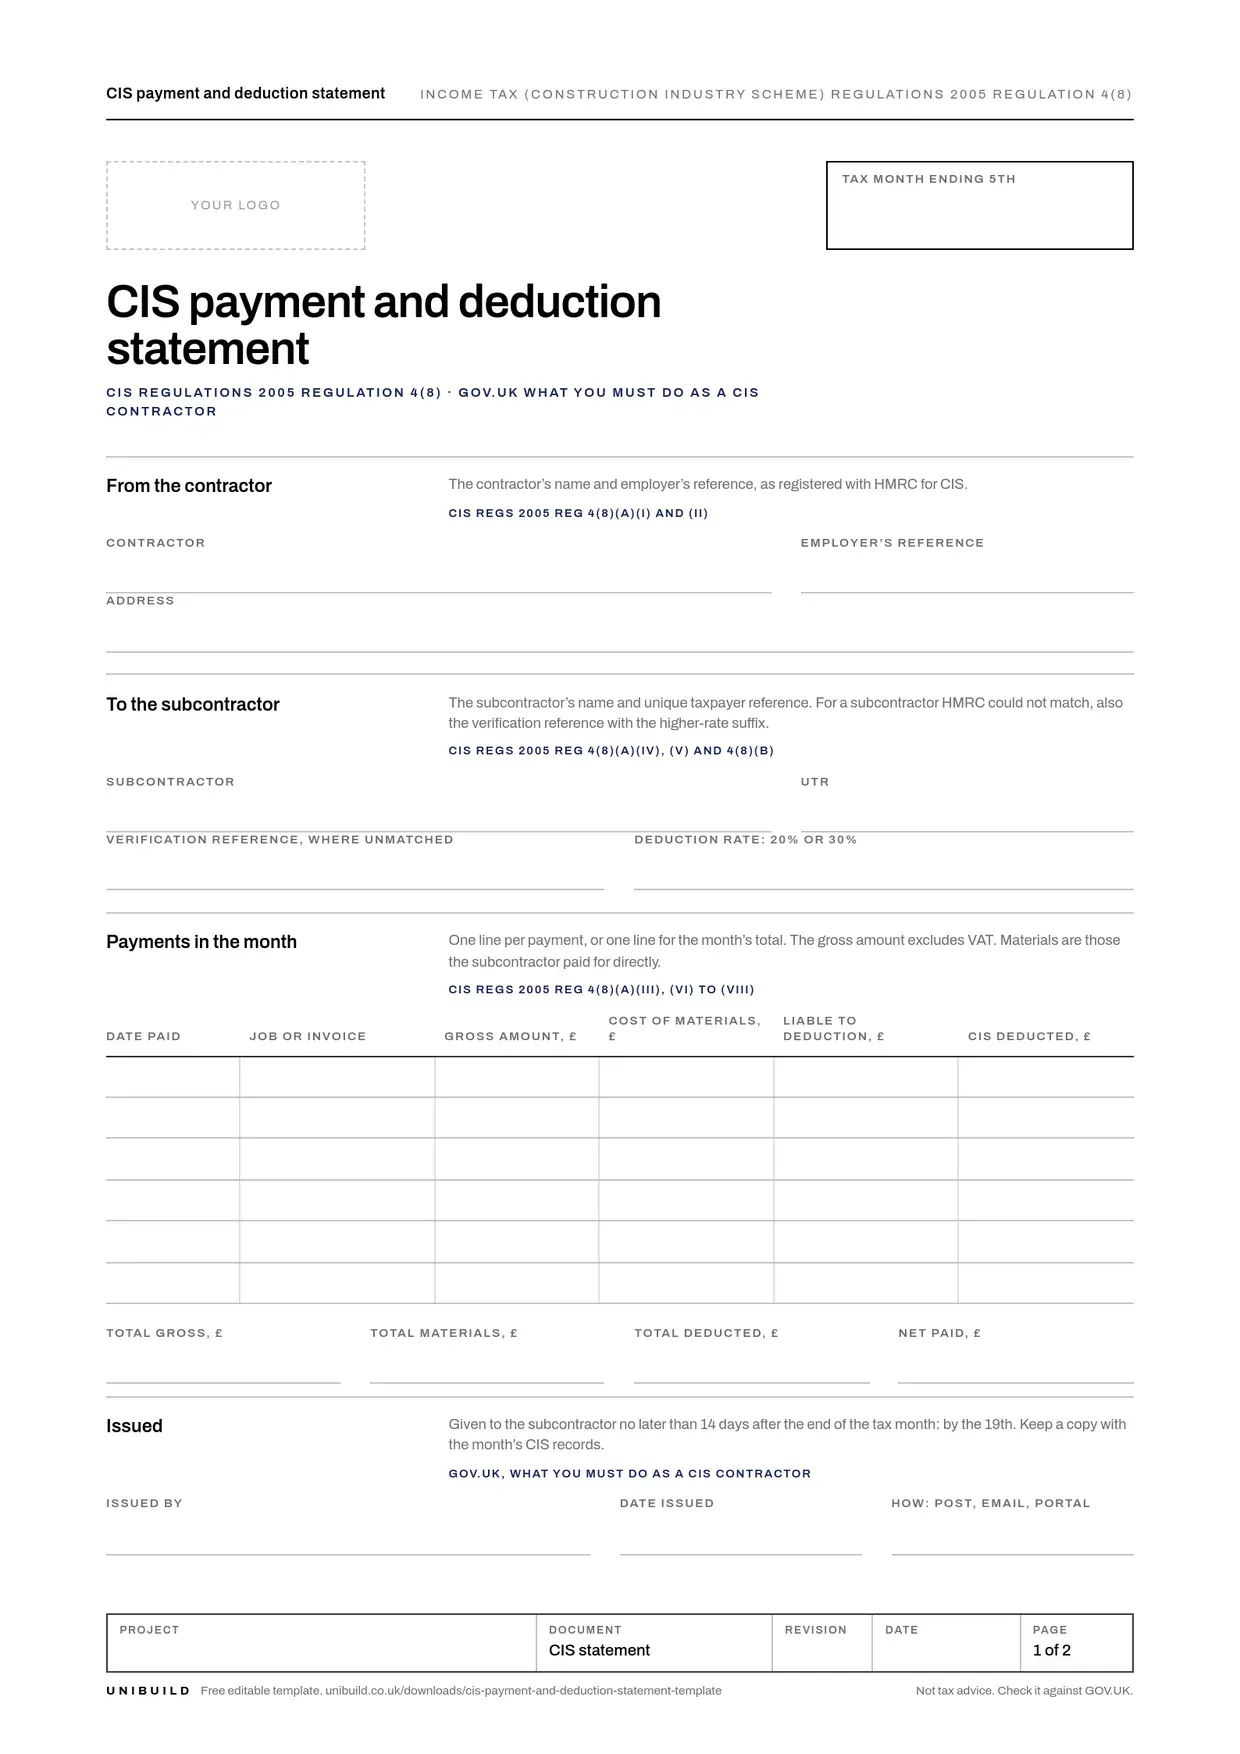
The contractor’s name, employer’s reference and address, as registered with HMRC for CIS.
Their name and unique taxpayer reference, the deduction rate, and the verification reference where HMRC could not match them.
Each payment in the month, or the month’s total: the date, the job or invoice, the gross amount and the cost of materials. Then the amount liable to deduction, the CIS deducted, the totals and the net paid.
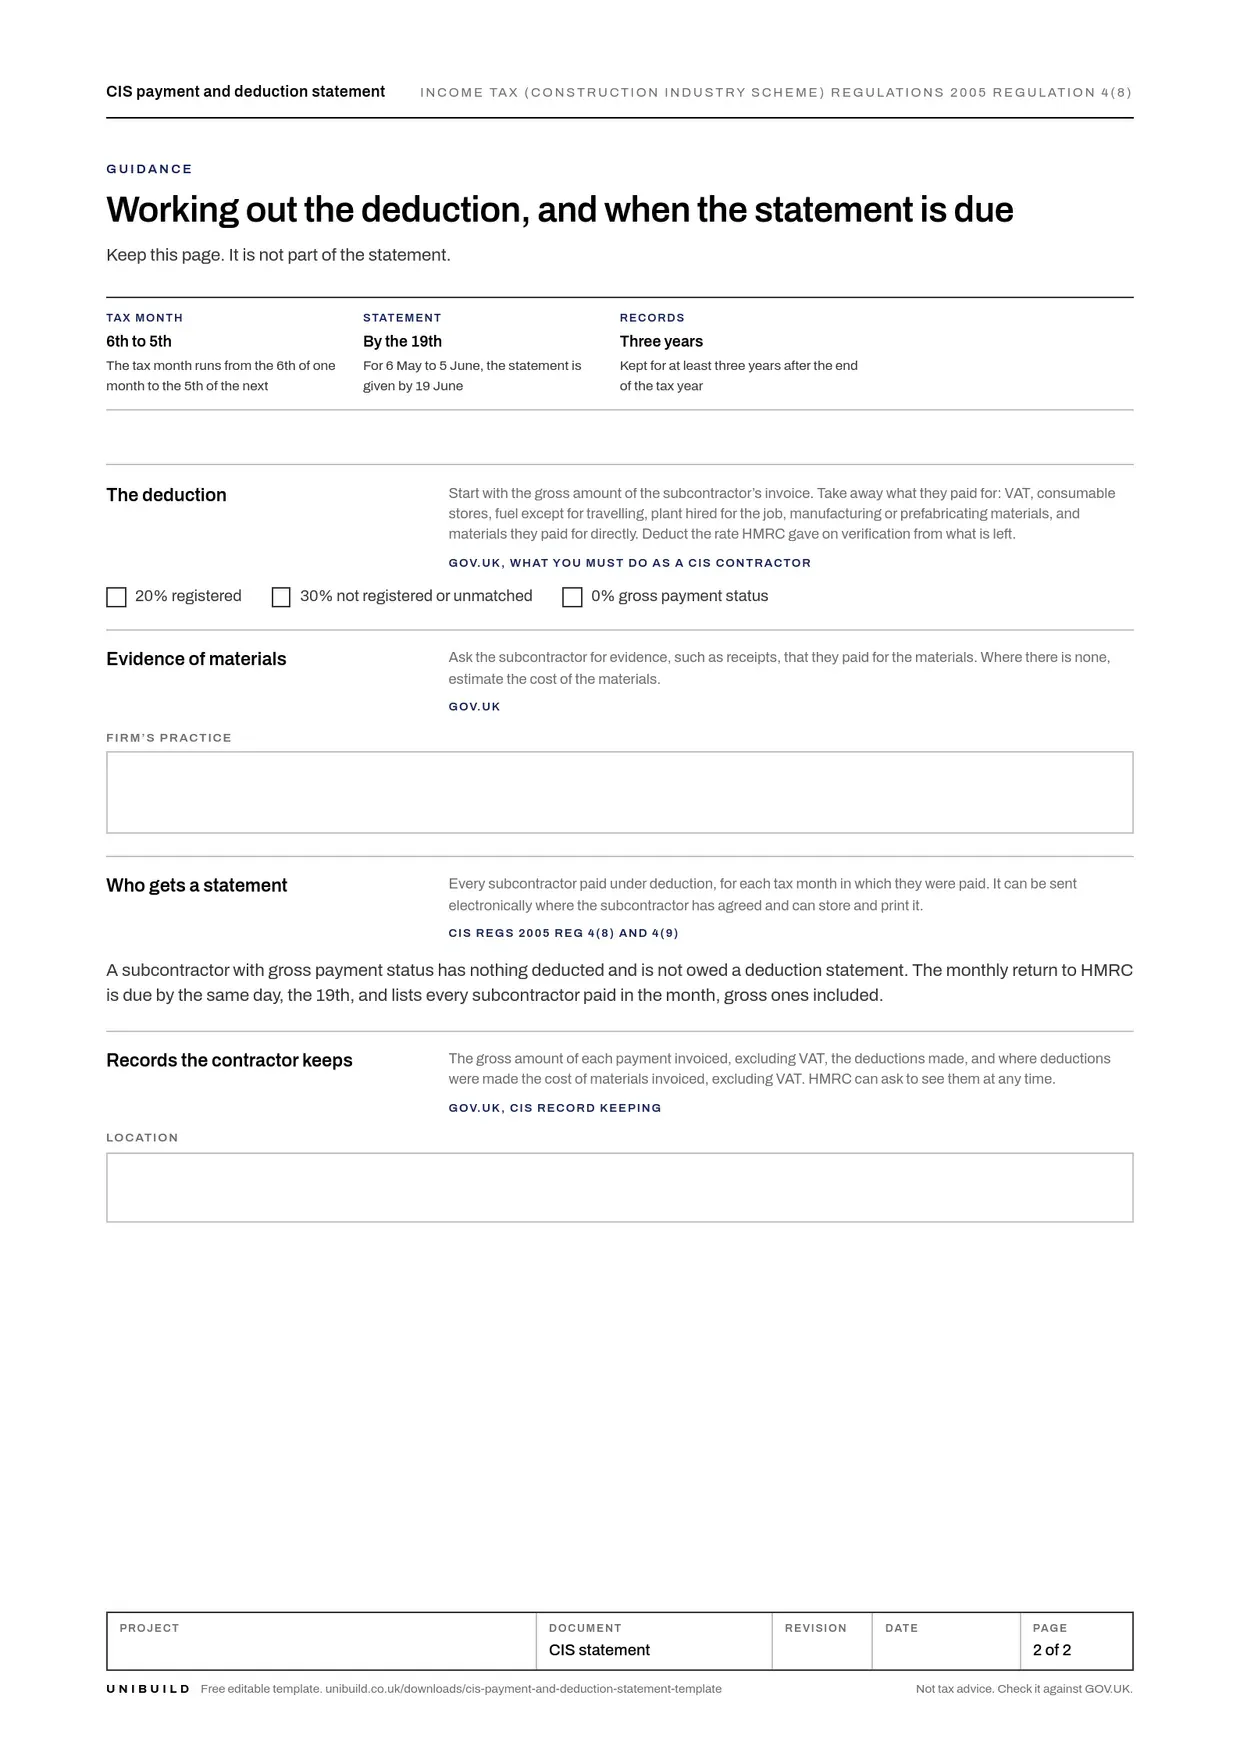
The tax month, the 19th of the month deadline, what comes off before the deduction, who is owed a statement and the records the contractor keeps.
The contractor’s name and employer’s reference, the tax month or payment date, and the subcontractor’s name and UTR. Then the total contract payments, the direct cost of materials in them, and the amount deducted. For a subcontractor not registered, the verification reference too.
Income Tax (Construction Industry Scheme) Regulations 2005, regulation 4(8)The statement is given no later than 14 days after the end of the tax month. For the month 6 May to 5 June, that is 19 June. It can be sent electronically where the subcontractor has agreed.
Regulation 4(8) and 4(9); GOV.UK, What you must do as a CIS contractorStart with the gross invoice. Take off VAT, consumable stores, fuel except for travelling, plant hired for the job, manufacturing or prefabricating materials, and materials the subcontractor paid for. Deduct 20%, 30% or 0% from what is left, at the rate HMRC gave on verification.
GOV.UK, What you must do as a CIS contractorThe rate on the statement comes from HMRC’s verification, not from the subcontractor’s invoice. A subcontractor HMRC cannot match is deducted at 30%.
Receipts for the materials the subcontractor bought. Where there are none, the contractor estimates the cost, and the estimate is the contractor’s to defend.
The return to HMRC and the statements fall due on the same day. In Unibuild CIS works to HMRC tax months, so the deductions, the return figures and each subcontractor’s statement come from the same payments.
A leave record per person with entitlement, carry-over and every request approved, a team planner a quarter per page, and the 2026 and 2027 bank holidays by nation. As a PDF, Word and an Excel workbook.
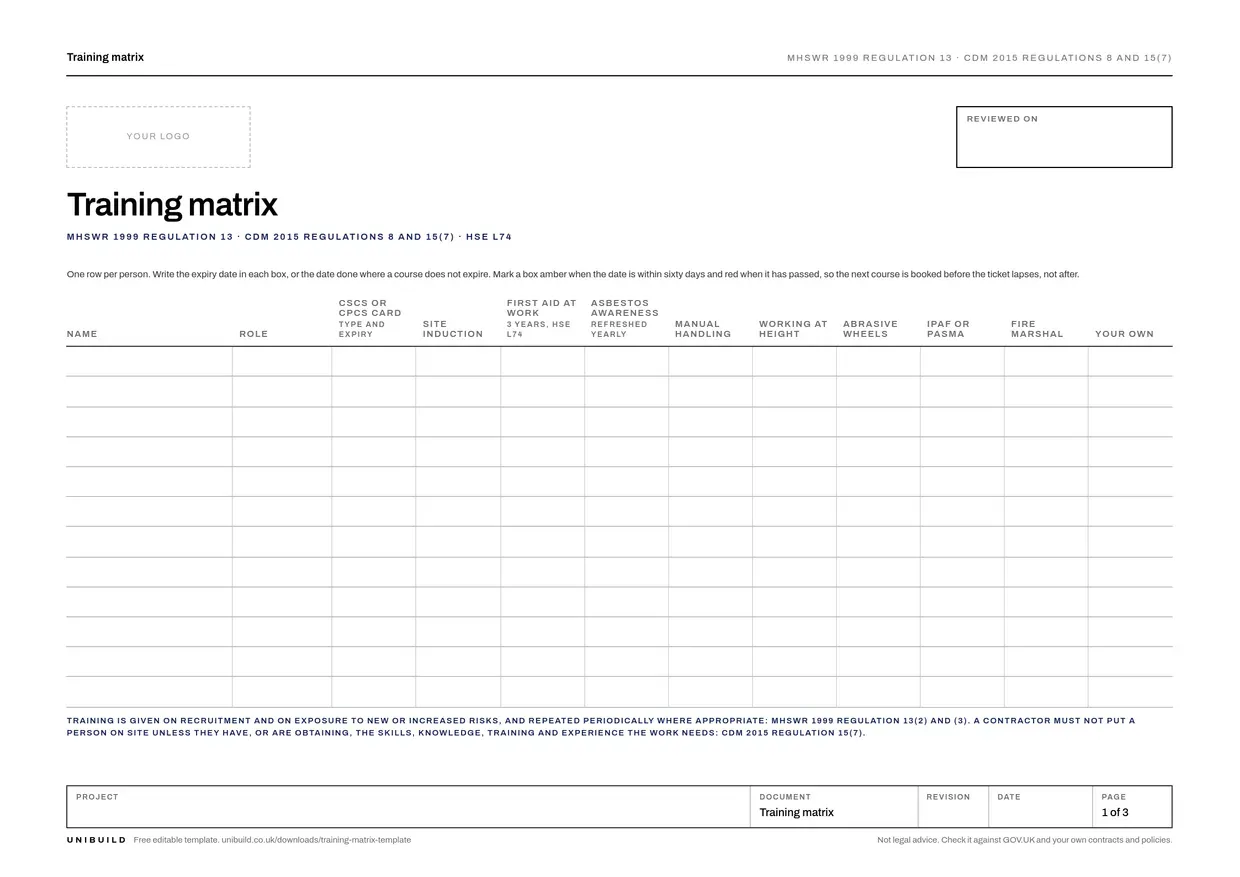
One row per person with the expiry of each card and course, a training record per person, and a training needs grid by role. As a PDF, Word and an Excel workbook that turns a date amber at sixty days and red when it passes.
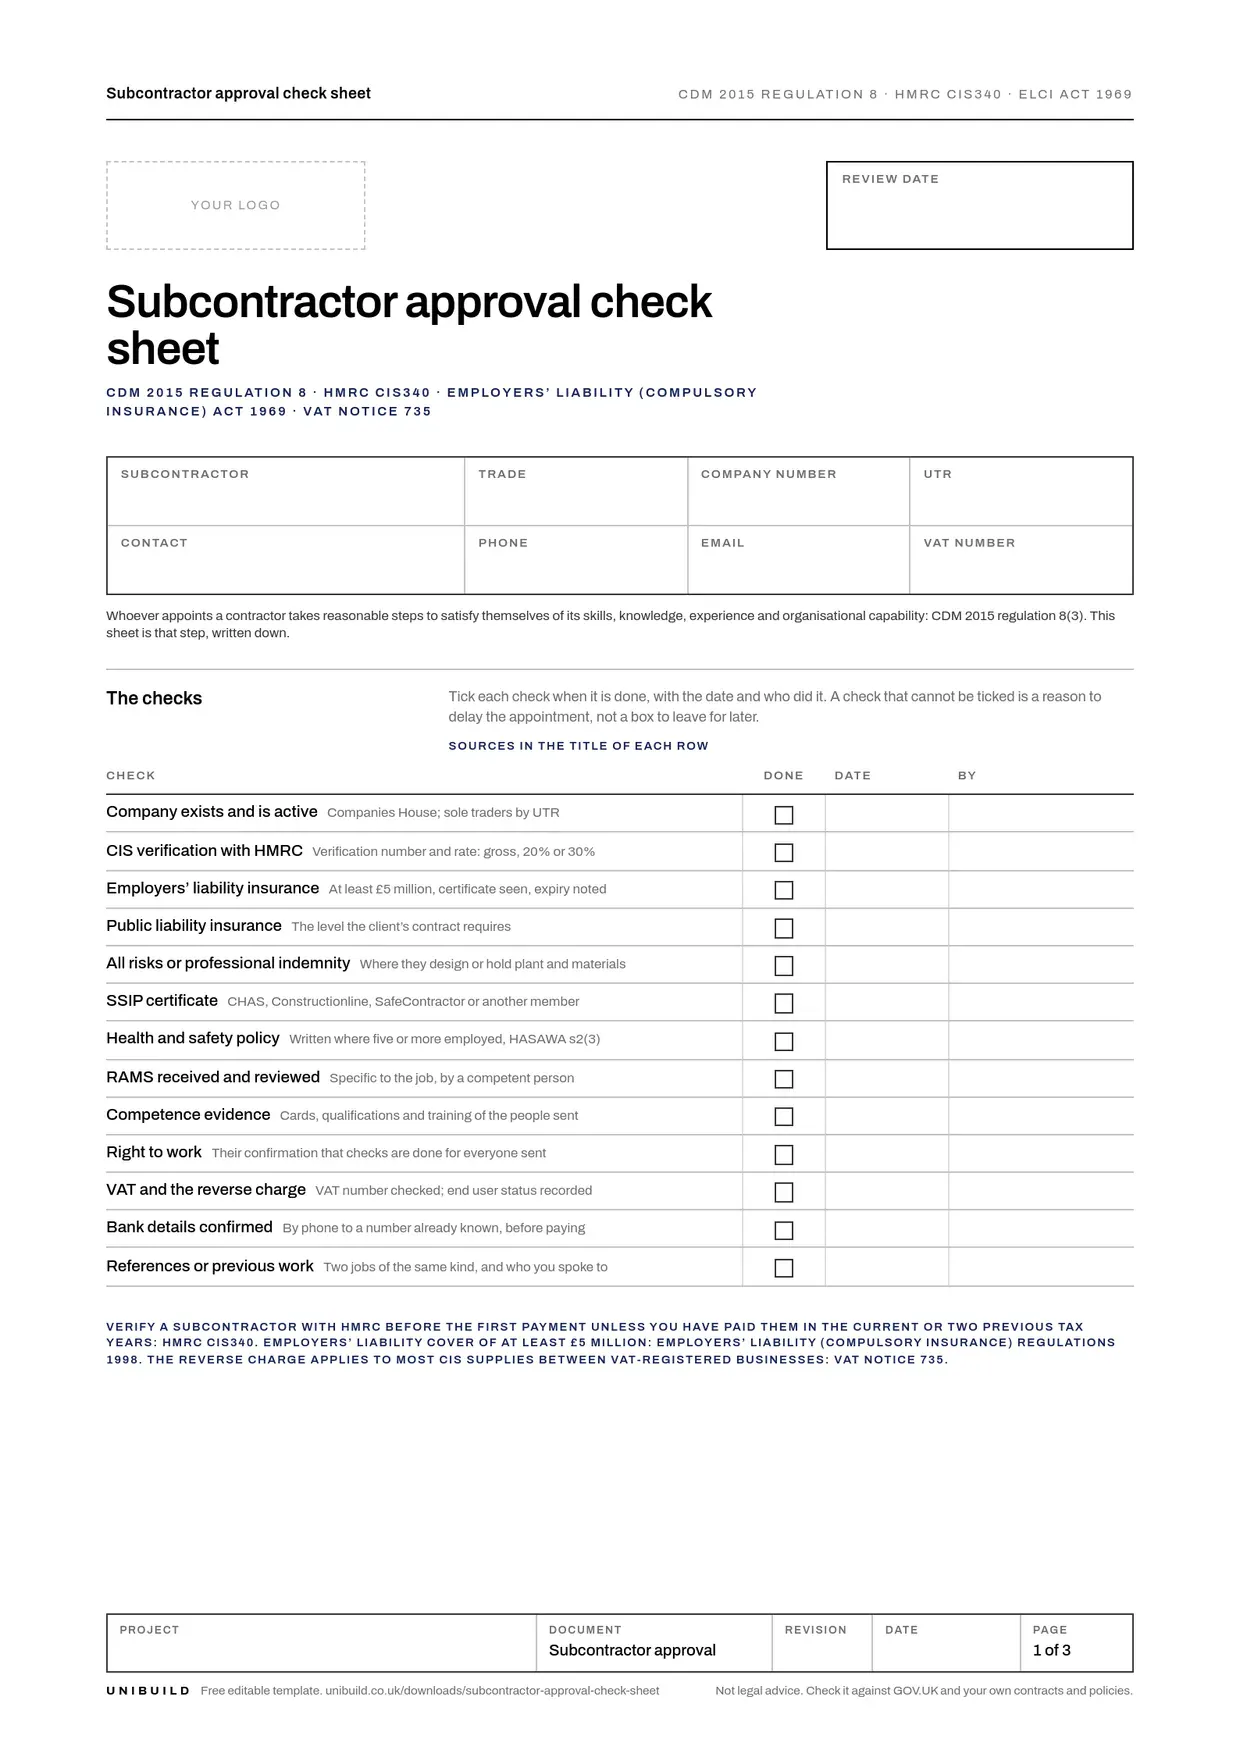
The checks before a subcontractor goes on the approved list: Companies House, CIS verification, insurance, SSIP, the policy, RAMS, competence, right to work, the reverse charge and bank details, then the decision, the register and the review log.
On the platform these stop being sheets. The check, the person, the date, the signature and the action that followed are recorded as the work runs and retrieved by site.
UK-built · CDM · CIS · MTD