
Stock control for a contractor:
the unit, the vans and the jobs.
Merchants count stock because stock is the business. Contractors rarely do, and pay in materials bought twice, fittings that never reached a job, and a year-end figure nobody believes.
Published ·Updated ·7 min read·Written by Darshan Parmar, Founder
Stock control for a contractor means knowing, at any moment, what materials the firm owns, where each of them is, what they cost, and which job they went to. A merchant does this because stock is the business. A contractor's materials are a cost on somebody else's job, so they are bought, used and forgotten, and the stock in the unit, the vans and the site containers is whatever nobody has got round to using yet. That is where the money goes. The fix is a record of quantity by location, updated when materials move, booked to the job they go to, and checked before anything is ordered.
Stock is in four places at once
A firm of two to four crews holds materials in four places at the same time, and each one fails in its own way.
- The unit. Racking, pallets, part rolls of membrane, half a pallet of insulation, boxes of trims and fixings from finished jobs. This is the stock everybody knows exists and nobody can list.
- The vans. Each one is a small stores on wheels, restocked from the unit and from the merchant on the way to site, and counted never. Fittings, adhesive, consumables and the odd expensive tool live here.
- The sites. Materials delivered direct to the job, kept in a container or under a sheet, used by whoever needs them, and left behind or brought back at the end without anybody recording which.
- On order. Committed to but not yet arrived. Invisible to anybody looking at a shelf, and the reason the same pallet gets ordered twice by two people on the same afternoon.
A spreadsheet can describe the first of these on the day it is written. It cannot follow the other three, because the movements happen on site, in a van and at a merchant counter, by people whose job is not administration.
Where the money actually goes
Nobody notices stock going missing. What they notice, eventually, is one of four bills.
Materials bought twice. A job needs insulation, nobody can say whether there is a pallet in the unit, so one is ordered. The order is a visible cost with an invoice against it. The pallet already in the unit is invisible, and stays so until the next move of premises forces everybody to handle it.
Materials that left in a van and never reached a job. A crew takes fixings, adhesive and trims out of the unit on the way to site. Nothing is booked to the job, so the job costing never sees it, and the margin on a fixed-price job is a guess by the amount that walked. Over a year this is usually the largest of the four, and the hardest to see because it never appears as a line anywhere.
Dead stock from finished jobs. The part roll, the opened box of trims, the twelve tiles kept for snagging. Each was paid for by a job that has closed, each is now worth something only if somebody knows it exists, and almost none of it is ever used.
The year-end figure. The accountant asks for a closing stock value and gets a shrug or a number invented on the spot. The Companies Act asks any company whose business involves dealing in goods for a year-end statement of stock and the stocktakings it was worked out from, and your accountant will ask for a closing figure either way. A number nobody believes is still a number on your accounts.
A contractor's stores is a merchant with one customer, and the same three questions: what is on the shelf, what did it cost, and where did it go.
What the record has to hold
Six fields, and it is the last two that turn a list into stock control.
- The line, described well enough that two people would pick the same thing off the shelf. A code helps; a photograph helps more.
- A quantity per location, not one quantity for the firm. Twelve in the unit, four in van two, six on the Exeter job. One number for all of them tells you nothing you can act on.
- The cost price, taken from the purchase order when the goods came in, so that whatever goes out to a job carries what it actually cost rather than a list price from a catalogue.
- Where it came from, meaning the order and the goods received note that booked it in. That is the subject of a separate article on goods received notes, and it is where the cost price comes from.
- The job it went to, recorded at the moment it left, by the person taking it. This is the field that makes the stock system and the job costing the same system.
- A movement history, so that a location is a current answer rather than the last time anybody updated a cell. Every in and out is an entry with a date, a quantity and a name.
Booking materials to the job is the part that pays
The first four fields keep the shelf honest. The fifth is where the money is, because it is the point at which stock control stops being a stores problem and becomes the job costing.
When a crew takes materials for a job, the quantity comes off the location it came from and lands on the job at cost. The job's materials figure is then the sum of what was ordered for it directly plus what was drawn from stock, on the day, rather than the sum of whichever merchant invoices happened to carry its reference. When the same crew brings the leftovers back, the reverse entry puts the value back on the shelf and takes it off the job.
That is what a fixed-price job's margin looks like while the job is still running. Without it, the materials figure is complete only when the last merchant invoice has been coded, weeks after the work, and anything drawn from the unit or the van is missing from it entirely. It is the same failure as the one in the job costing spreadsheet, seen from the shelf rather than the desk.
What a merchant does that you can copy
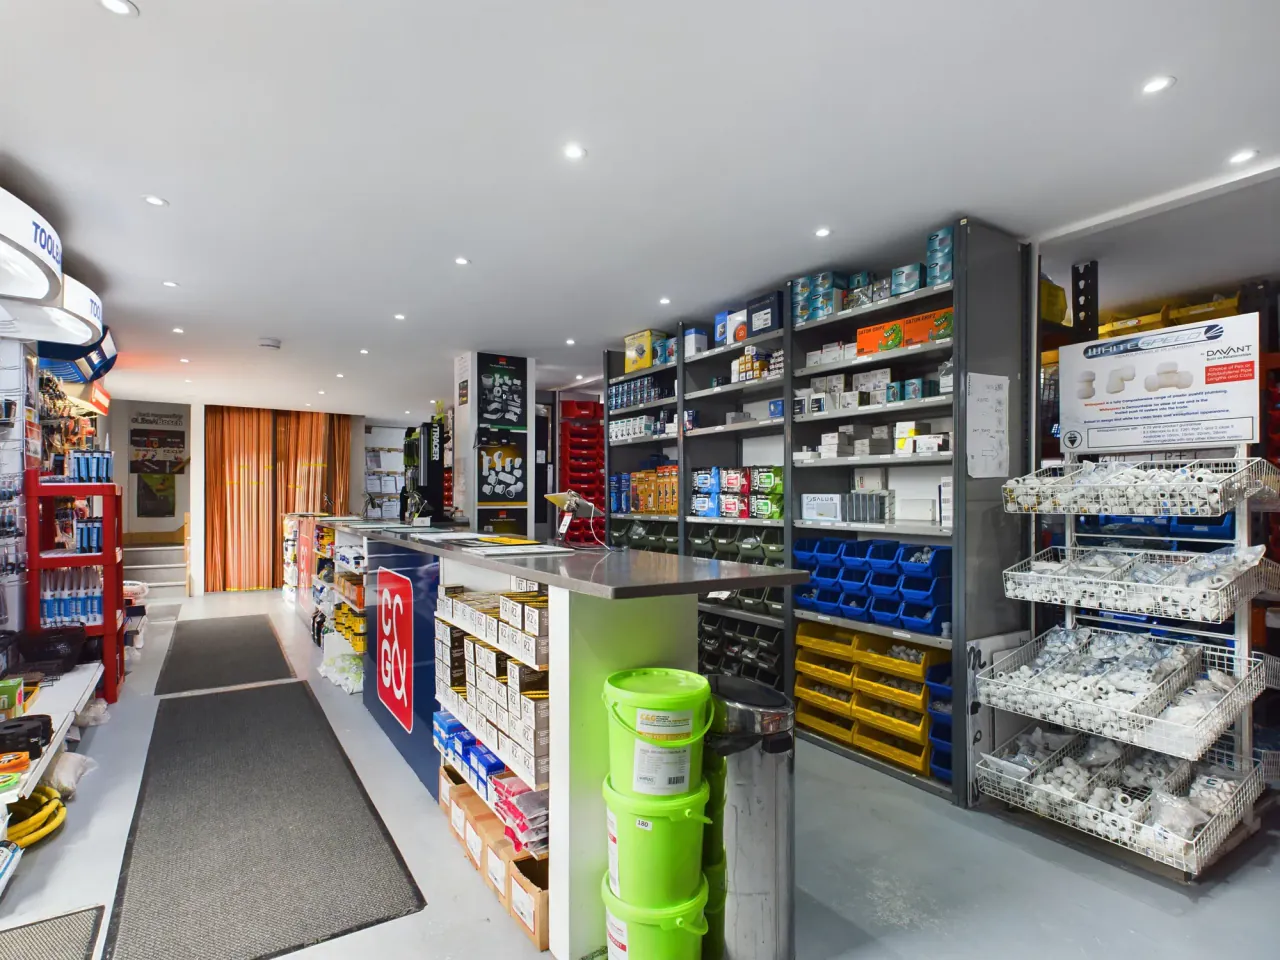
C&G Heating & Plumbing Supplies is a merchant in Erith with a separate bespoke catalogue and tablet-counter system whose history dates to November 2017. Its 3 September 2026 case-study snapshot reports 72,444 catalogue product records, not 72,444 physical stock units. The study describes counter and account workflows, not independently measured stock accuracy.
For a contractor’s stores, the general principle is to connect the record to the movement: record the line, quantity, location, date and person, and reconcile the record with physical checks. Recording a sale at a counter illustrates point-of-work capture, but it does not by itself prove that all stock movements are recorded correctly. Nor does C&G’s case study establish routine purchase-order or goods-received-note adoption.
Change "across the counter" to "out to the job" and that is a contractor's stores. The paperwork is identical. Only the direction of the last movement is different.
When the spreadsheet stops being enough
A spreadsheet works while one person does all the buying, all the checking and most of the fetching, because that person is the movement record. It stops working at the second van, the second buyer or the second concurrent site, whichever comes first, and it stops quietly.
The signs, in the order they usually arrive: a pallet ordered that was already in the unit; a merchant invoice nobody can put against a job; a crew ringing to ask whether there is any of something left; a closing stock figure that took a weekend and is still a guess. By the fourth the spreadsheet has been wrong for a year.
What contractors move to
Three routes, and each suits a different shape of firm.
- A better spreadsheet. One file, a quantity per location, and a weekly count of the twenty lines bought most often. It holds while one person does all the buying.
- Off-the-shelf stock or job software. A stock list on a phone, booked in against the order and out to the job. The unit and the vans work to the product's process.
- A bespoke platform. Stock, purchase orders and job costing on one record, shaped to how the unit, the vans and the sites already run.
The route matters less than where the entry is made. Whether that is a stock module on the system that runs the rest of the firm, or a system written around one counter as C&G's was, the test is the same: is the movement recorded at the moment it happens, by the person making it, on the device in their hand. Anything that depends on somebody remembering to update a file when they get back to the office will be accurate for about a fortnight.
Unibuild sits in the third group: bespoke business software for trades that has run a stores operation since 2016, shaped to each firm's own way of working. In assets and inventory, one register holds every tool, machine and pallet, with a quantity per named bin. The number on the screen is the number on the shelf, so the unit can be checked from a desk before anything is ordered.
Materials are requested from site, approved by the store, picked against the real bins and serial numbers, and booked against the project on the day. Delivery is signed for in the firm's own staff app, published under its company name and icon. Collections bring the leftovers back onto the shelf and off the job. Goods received against the purchase order, deliveries out and collections back run through one continuous stock ledger, which refuses to promise materials that are not on the shelf.
Where to start, on Monday
Not with a full count. Take the last five invoices from your main merchant and, for every line on them, write down which job it went to. Then walk to the unit and see whether any of those lines are still sitting there.
Whatever you cannot answer, and whatever you find on the shelf that was bought for a job that has closed, is the size of the problem. It is also the size of the record you need, which is usually smaller than a firm expects: the twenty lines it buys every week, held by location and booked to a job when they leave, would have caught most of it.
Sources
Checked against the source rather than against commentary. Where a schedule, a rate or a threshold is definitive on a government site, read it there.
The follow-up questions.
The tools and plant side of the same problem is in knowing what plant you own and where it is.
How do contractors keep track of materials across several jobs?
Where does contractor stock actually go missing?
How do we stop buying materials we already have?
How do I stop buying materials we already have?
Does a contractor have to do a stocktake?
Do contractors need to do a stocktake?
What is the difference between stock control and an asset register?
What is the difference between stock and materials on site?
Is a spreadsheet enough for stock control?
At what point is a spreadsheet no longer enough?
Know what is on the shelf, and which job it went to.
Bring your stock spreadsheet, or the merchant invoice nobody could put against a job. Half an hour on the live system is usually enough to tell.
- Thirty minutes, weekdays, from tomorrow.
- Nothing to prepare. Bring a job number and we mock that job up.
- You drive it. There is no slide deck.
- You keep what you saw as a 14-day trial. No card.
More from Insights.
 Goods received notes, and why stock should arrive on an orderA delivery note proves a van turned up, not what was ordered, what was on the pallet, or what the supplier is about to charge. The goods received note is where those three are made to agree.Read it →
 Off-hire, and the charges that keep runningHire runs until the item is off-hired, not until you finish with it. A preventable loss that every contractor recognises and almost nobody has a process for.Read it →
 LOLER, and the clock on every lifting accessorySix months for anything that lifts people, twelve for everything else, and a report that has to exist before the next lift. What thorough examination means, and what it is not.Read it →
All 6 articles on plant and assets.